
How a Return of Russian Diesel Exports Could Change MR and LR Employment
Disruptions to refining and exports from Russia and the Middle East have put diesel under particular pressure this year. European diesel refining margins reached a record of nearly US$ 95 per barrel in September and the IEA expects the gasoil market (diesel and heating oil) to stay tight in H1 2027, with the stocks lost during the disruption unlikely to be rebuilt before H2 2027. In the US, the EIA average road diesel price stood at US$ 6,276 per gallon on 19 October, about 73% above a year earlier, ahead of the 3 November midterms.
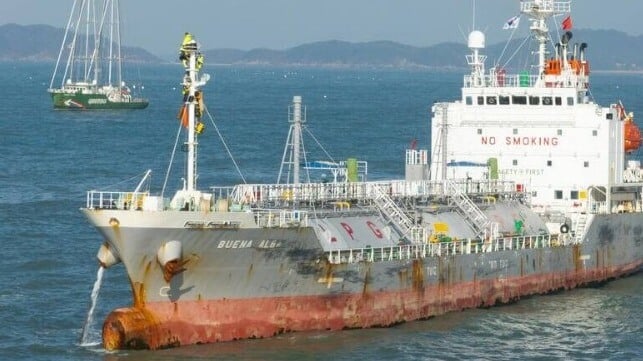
On 9 October, following a US-Russia deal to release Russian diesel to the global market, OFAC issued General License 135. Until 7 April 2027, it allows the sale, delivery and import of Russian-origin diesel, including into the US, that would otherwise be prohibited under the US sanctions regulations it names. Russia eased its own diesel export ban at the same time and cargoes to Turkey and Brazil resumed in mid-October, according to Reuters. Since Russian supply fell earlier this year, many MRs and LRs have been employed carrying replacement diesel from the US Gulf, the Middle East Gulf and India. How that employment changes in 2027 depends on whether and where Russian exports return.
Replacement Trades in 2026
Brazil, a regular buyer from both Russia and the US, shows the switch most clearly. Based on data from Signal Ocean, Russian diesel loadings for Brazil averaged about 528.000 tonnes a month in H1 2026, then fell to about 23.000 tonnes a month in Q3, after Russia banned exports of diesel and other gasoils in July following Ukrainian drone strikes on its refineries. Over the same periods, US Gulf loadings for Brazil rose from about 250.000 to about 753.000 tonnes a month. US Gulf loadings for Brazil reached 3,76 million tonnes across 122 voyages in January to September 2026. MR2s carried 62,8% of this volume, LR2s 23,6% and LR1s and MR1s the remaining 13,6%, against an MR2 share of 90,7% across all US Gulf diesel exports.
Turkey followed the same pattern. Russian diesel loadings for Turkey fell from about 743.000 tonnes a month in H1 2026 to about 90.000 tonnes a month in Q3, as the same July export ban took effect. Across Europe, S&P Global reports that replacement diesel has come from the Middle East Gulf, India and the US Gulf, with long-haul LR voyages replacing the short Baltic MR voyages that historically supplied Northwest Europe. Middle East Gulf supply is itself uncertain: Hormuz traffic remains well below normal and the IEA warns that further attacks could delay the recovery in its exports and LR cargoes.
Effect of the Return of Russian Cargo Flows
Russian loadings for Brazil have shown little recovery so far, at about 40.000 tonnes during 1-23 October. Brazil has previously bought large volumes of Russian diesel when it was cheaper than US supply and Russia was at times its largest foreign supplier. Under the programme announced by President Trump, Russia would supply 300.000 tonnes of diesel immediately, 500.000 tonnes in November and 1 million tonnes after that, with a further 3 million tonnes later depending on the condition of its refineries. The full 4,8 million tonnes equals about nine months of Brazil-bound Russian loadings at the H1 2026 rate, although the announced volumes concern US and global markets rather than an allocation to Brazil. Reuters reported on 23 October that the first cargo under the deal, about 40.000 tonnes, was heading to New York, which would reopen a long-haul route closed since the 2022 US ban on Russian oil imports.
If Russian barrels return, the effect on ship demand differs by market and by loading port. Turkey sits next to Russia's Black Sea ports, so each Black Sea cargo that replaces a US Gulf or Indian one would free a large amount of tanker time. Black Sea exports have been disrupted by attacks on Novorossiysk and Tuapse, however. According to Reuters, the first restart cargo for Turkey loaded instead at the Baltic port of Primorsk, a much longer voyage. For Brazil, returning Baltic supply would not necessarily shorten voyages.
The displaced US barrels would then need another outlet. Signal Ocean data show that US Gulf diesel loadings for Europe totalled 5,01 million tonnes in January to September 2026, up about 16,5% on a year earlier, but only about 150.000 tonnes during 1-23 October, against 260.000 tonnes a year earlier. Kpler assessed on 21 October that higher freight had closed the US Gulf to Rotterdam arbitrage for November arrivals, although some cargoes can still move.
According to Clyde & Co, the licence could end before April because it sits in tension with the 2022 US ban on Russian oil imports and may face legal challenge. The licence does not delist sanctioned vessels, so each transaction still needs checking against the vessels and parties involved; UK and EU bans on Russian diesel also remain in force. Reuters reported on 21 October that operators were reluctant to carry Russian diesel because later customers might reject the ship. Charterers would still need to assess each vessel's insurance, classification, ownership and trading history. How many ships now in Russian trades move into mainstream trades and how quickly is not yet known. If many do, more vessels would compete for the same cargoes, which could weigh on freight rates.
Outlook for 2027
On balance, the market reading for 2027 is supportive for product tanker employment but uneven across segments and trades. Two factors could sustain import requirements in 2027. The first is timing: high margins have led refiners to defer maintenance into 2027. Industrial Info Resources reports that turnarounds at ten crude units across seven US refineries have moved to autumn 2027 and Morgan Stanley expects unusually heavy global maintenance through Q2 2027, so replacement cargoes may still be needed, where other exporters can supply them, after the licence expires on 7 April, or earlier if it is withdrawn. Deferred maintenance could also prolong the usual diesel cycle, in which high margins draw more refinery runs until supply catches up and margins fall.
The second is stock rebuilding: importers refilling storage would need extra cargoes, even though global diesel demand has fallen year on year. Stocks were also drawn down in Q3, when they normally build ahead of the northern hemisphere winter, so seasonal heating demand starts from a lower base and a colder than normal winter in Europe or the US Northeast would tighten the market further.
The implications also differ by trade. In Turkey, a recovery in Black Sea loadings could replace longer voyages with much shorter trips where they displace supply from more distant exporters, so long-haul cargoes serving that market are the most exposed. In Brazil, a Russian return may not shorten voyages, so the effect on MR2 and LR2 demand depends on whether the displaced US Gulf barrels find another outlet. On this evidence, the reading for MRs is cautiously positive: continued US Gulf exports and stock replenishment could support employment, although a Russian return could displace some replacement cargoes. The outcome for LRs depends on which longer voyages remain necessary. The effect will not stay in diesel; MRs and LRs also carry gasoline, jet fuel and naphtha, so ships that lose diesel cargoes will compete for these cargoes instead, while ships kept busy in diesel leave fewer vessels for them.
The views expressed in this article are the author's own and do not represent the views of GMS.
By Xakousti Merika